On September 29, at the State Council Information Office press conference on starting the 15th Five-Year Plan, Chen Bangxun,spokesperson of the Ministry of Agriculture and Rural Affairs and head of its Development and Planning Department,reported the latest progress in hog capacity regulation: by the end of the second quarter, the national breeding sow inventory had been reduced to 37.8 million head,back within the green and reasonable range of the capacity-control regime; going forward, precise capacity regulation will be carried out on a routine basis,and the ministry explicitly pledged to “push hog farming toward better quality, higher efficiency and lower costs”. Market data, however, is far from reassuring.According to China National Radio on September 30, the national average price of external three-way hogs fell to 10.17 yuan/kg in September,down 8.87% from the start of the month, and self-breeding farms are losing about 210 yuan per head — losses that have now lasted more than a year.Policy calls for cost cuts while the market keeps losing money,and the whole hog chain is hunting for new profit space. For slaughtering and processing enterprises,one of the most direct answers hides in what remains after each pig is cut up: bones, fat, offal and blood.
The Second Income Is Growing Heavier
Slaughter volumes are still climbing. Take the ministry’s designated monitoring point in Anhui: in August the province’s designated hog slaughter volume reached 1.7409 million head,up 17.81% year on year, and the national figure is similarly running high. Every additional pig slaughtered means more bones, fat,offal and blood — by-products that used to have only two ways out: sell them cheap downstream,or pay a disposal fee to send them away. The National Livestock and Veterinary Industry Development Plan for the 15th Five-Year Period,issued in early September, has explicitly written “strengthening the comprehensive development and utilization of by-products” into its task list.In the plan, by-products are no longer a passing mention but a named space for value-added growth.As the margin on wholesale carcass meat gets thinner, this “second ledger” naturally carries more weight.
Costs Rise, Prices Fall: the Gap Is Filled Here
Costs and selling prices are moving in opposite directions.National Bureau of Statistics monitoring shows that in early September soybean meal (crude protein ≥ 43%) was priced at 3,305.8 yuan per tonne,up 3.7% period on period, while hog (external three-way) prices stood at 11 yuan/kg, up only 0.9%,slipping further to 10.7 yuan/kg by mid-September. Feed costs rising while hog prices fall —this scissors gap is turning “cost reduction and efficiency” from a slogan into a survival issue.For slaughtering and processing enterprises there are in fact two ledgers:one for carcass meat sales, one for by-product output. When the first gets thinner, the second matters more —all the more so because animal fat and protein meal are themselves feed ingredients,standing exactly on the rising end of the soybean meal price. The downstream output of the chain hedges the upstream cost.
Same Raw Material, the Process Decides the Ledger
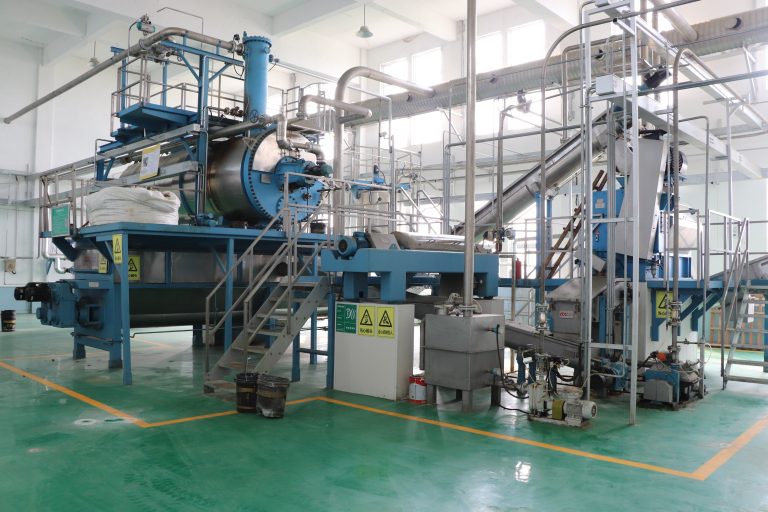
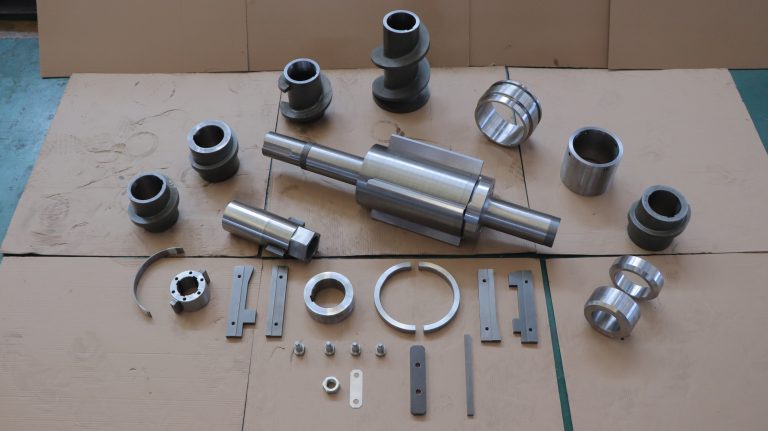
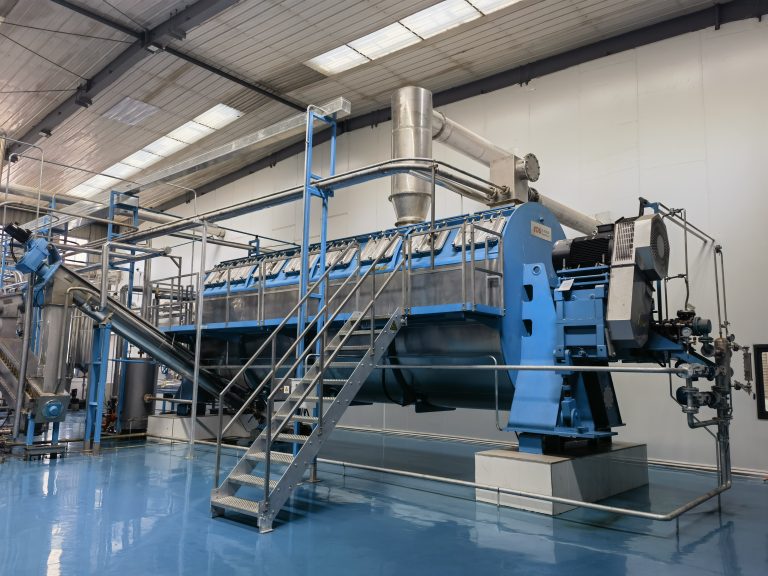
When by-products fail to turn into money, it is usually stuck at three points: oil yield, protein meal quality, and whether waste gas treatment meets the standard.If the temperature and holding time in batch cooking are insufficient, the oil is not fully released and the protein poorly denatured;the configuration of the screw press determines the residual oil in the press cake;the drying step (a Disc Dryer, for instance) directly affects the color, moisture and digestibility of protein meal;and if waste gas treatment falls short, environmental acceptance stalls, and every idle day of the line is a pure loss.In other words, the variable in this ledger is not the raw material but the production line — hourly capacity, continuous operation rate,steam and power consumption all fold into one indicator:processing cost per tonne of raw material. Two lines handling the same material can differ by an order of magnitude on paper because of equipment configuration and process route.
At the Bottom of the Cycle, It Is Time to Do the Math
When hog prices sag, caution about equipment investment is a natural instinct. But the 15th Five-Year Plan also states another sentence: “promote the upgrading and transformation of slaughterhouses and eliminate outdated capacity.”The window for upgrading and the window of policy-driven shakeout actually overlap. More importantly,the by-product line is one of the few investments that improves cash flow at the bottom of the cycle — it does not depend on a price rebound:the more pigs slaughtered and the more abundant the raw material, the better this ledger reads. The rational path is to do the math first:how much oil and how much meal each tonne of raw material yields, what the processing cost is, and where the products sell. Once the numbers are clear, decide how to configure the line.
Hebei Chengzhu Machinery Group specializes in equipment for the resource utilization of slaughterhouse by-products, offering comprehensive solutions that cover everything from crushing, cooking, and pressing to drying and exhaust gas treatment. Amidst an industry-wide shift toward re-evaluating economics, the company helps clients transform every fraction of their raw materials into measurable output.



 Blog · 10 月 14, 2026 From Smart Ear Tags to Processing Records: The Data Chain the “15th Five-Year” Livestock Plan Wants to Connect Read More